Key Takeaways
- Start with dates, records, amounts, and direct observations rather than conclusions.
- Preserve relevant evidence lawfully and avoid changing, deleting, or widely sharing it.
- Choose a reporting channel based on the suspected conduct and the people involved.
- Keep a private timeline of reports, responses, and potential retaliation.
- Do not confront a suspected wrongdoer or attempt to conduct a full investigation alone.
- Protections and reporting procedures can vary by agency, industry, and type of disclosure.
Suspecting workplace fraud can put an employee in a difficult position. The most effective response is usually calm, factual, and lawful: document what you directly know, preserve relevant materials without altering them, and use an appropriate reporting channel. Employees who have concerns about reporting options or possible retaliation may also consider speaking with Brown, LLC about their circumstances.
Why Careful Reporting Matters
A well-organized report helps employers, regulators, or investigators assess potential losses, false billing, theft, misuse of funds, or inaccurate compliance records. It need not solve the case—just provide enough reliable information to determine whether further review is warranted.
For example, repeated vendor invoices for work missing from project logs or site records may raise concerns. Though this alone does not prove fraud, the invoices, dates, work records, and names can give the organization a useful starting point.
What Counts As Workplace Fraud?
Workplace fraud generally involves intentional deception for personal gain or to cause financial loss. It can occur in private businesses, nonprofit organizations, government offices, and regulated programs. Common warning signs may include:
- False invoices, duplicate billing, or payment requests for services not provided.
- Falsified time records, expense reports, sales figures, or inventory records.
- Kickbacks, undisclosed conflicts of interest, or improper payments.
- Misuse of company funds, government funds, property, or confidential data.
- False certifications, compliance documents, or financial reports.
Not every error is fraud. A bookkeeping mistake, misunderstood procedure, or poor recordkeeping may require correction but may not involve intentional deception. A careful report should describe the facts and avoid assigning motives that cannot be supported.
Step 1: Write Down What You Know
Before reporting, create a simple factual record. Write down what you personally saw, heard, received, or reviewed, while the details are still clear. Include:
- The names, job titles, departments, vendors, or customers involved.
- Exact dates, times, locations, account numbers, and amounts when known.
- The specific record or event that raised concern.
- What you know directly, separated from assumptions or information provided by someone else.
- Whether the conduct appears ongoing or poses an immediate safety, financial, or evidence-preservation concern.
Step 2: Preserve Relevant Evidence
Preserve the original emails, invoices, messages, reports, policies, and meeting notes relevant to the concern. Use clear file names that include the date and a short description. Keep a record of where each item came from and when you received it.
Do not edit screenshots, alter documents, delete information, access systems without authorization, or take broad collections of confidential data. Customer, patient, employee, and financial information may be subject to workplace rules or legal restrictions. Avoid secret recordings or other evidence-gathering methods that could create separate legal or employment risks.
Step 3: Build A Simple Evidence Log
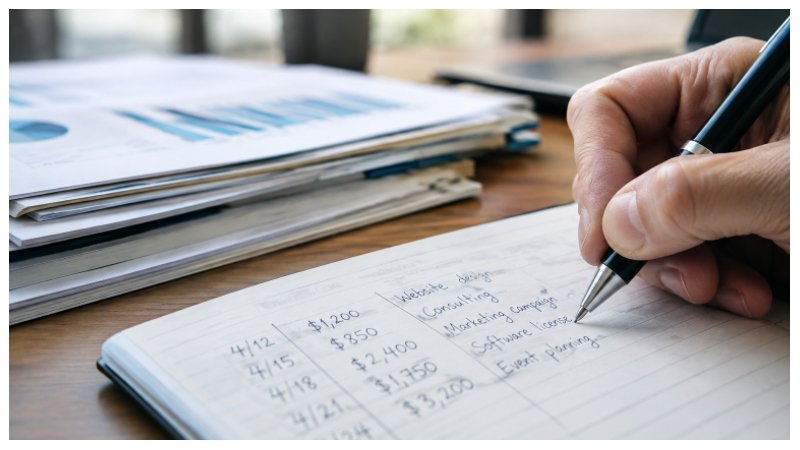
An evidence log can make a complicated concern easier to explain. A spreadsheet, notebook, or dated document can work. For each item, list:
- Date: March 4, 2026.
- Event: An invoice listed work that was not observed at the project site.
- Source: The invoice and the related project log.
- Why it matters: The records may indicate possible false billing.
- Action taken: Saved the records through an authorized method and noted the discrepancy.
Step 4: Choose The Right Reporting Channel
The best reporting path depends on the issue and whether leadership is involved. A supervisor may be suitable for a limited policy concern when that person has no conflicts of interest. Compliance, ethics, internal audit, or an ethics hotline may be better suited to suspected fraud, bribery, conflicts of interest, or accounting irregularities. Human resources may be relevant when retaliation or workplace conduct is also involved.
External reporting may be appropriate where public funds, taxes, securities, safety requirements, or regulated programs are implicated. Federal agencies do not all use identical systems for confidentiality, retaliation complaints, or potential awards. The different mechanisms used by federal agencies to protect people who report wrongdoing are one reason to review the specific agency’s instructions before submitting information.
Step 5: Review The Reporting Policy
Check the employee handbook, code of conduct, contract, compliance portal, or hotline instructions. Look for anonymous reporting options, procedures for urgent concerns, and methods for receiving a confirmation or report number. Save the version of the policy that applies when you make the report. An internal policy may be useful, but it does not necessarily replace an external reporting option or a deadline for a legal claim.
What To Include In A Report
- A brief summary of the concern.
- The names, roles, departments, or entities involved.
- Relevant dates, locations, amounts, and transaction details.
- The records that support the concern and where they can be found.
- The reason the conduct may violate a policy, contract, law, or program requirement.
- Any immediate concern about safety, ongoing losses, destroyed evidence, or retaliation.
What Not To Do Before Reporting
- Do not confront the person you suspect or announce that you intend to report them.
- Do not post accusations on social media or share information broadly with coworkers.
- Do not exaggerate the scale, certainty, or financial impact of what you observed.
- Do not alter records to make them easier to understand.
- Do not promise witnesses a particular investigation result.
How To Reduce The Risk Of Retaliation
Keep communications professional and fact-based. Retain copies of report confirmations, reference numbers, performance reviews, schedule changes, warnings, and messages related to your work. If unusual treatment follows a report, record the date, people involved, what happened, and any documents that support your account. Seek timely guidance if you face threats, demotion, termination, harassment, or other adverse action.
What Current Fraud Research Shows
The Association of Certified Fraud Examiners reported that tips accounted for 43 percent of fraud detections in the cases reviewed for its 2026 study, and more than half of those tips came from employees. Its 2026 occupational fraud findings reinforce why organizations benefit from clear reporting channels and prompt, fair review. A tip is not proof of wrongdoing, but it can provide information that would otherwise go unnoticed.
What Happens After A Report?
After intake, an organization may assess the allegation, preserve records, check for conflicts, interview relevant people, review transactions, or refer the matter to another department or agency. The reporting person may not receive full details because of privacy, employment, or investigative considerations. A lack of immediate updates does not necessarily mean the report was ignored.
Common Questions
Do You Need Complete Proof Before Reporting?
No. Provide accurate facts and supporting records that are available to you. The receiving organization decides whether further investigation is needed.
Can A Report Be Anonymous?
Some reporting systems accept anonymous submissions. However, anonymity can make follow-up questions more difficult, so review the specific process before reporting.
What If Your Supervisor Is Involved?
Use another approved channel, such as compliance, internal audit, an ethics hotline, human resources, or an appropriate government agency.
Conclusion
Reporting workplace fraud does not require solving the entire case on your own. A stronger approach is to document the facts, responsibly preserve evidence, select a suitable reporting channel, and avoid conduct that could compromise the information or create new risks. Clear, good-faith reporting gives decision-makers a better basis for reviewing the concern while helping the reporter protect their own position. Click here for more Information.