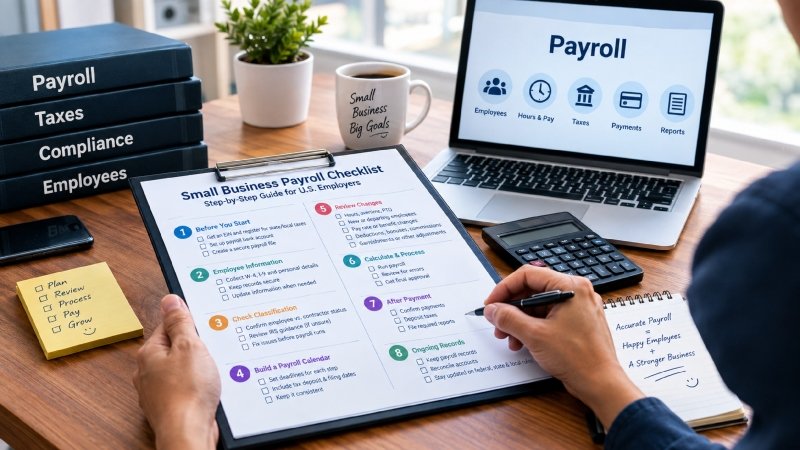
Payroll is one of those business tasks that needs to be accurate every time. A missed deadline, incorrect employee information, or overlooked change in hours can create extra work for an employer and potentially lead to tax or wage problems. The good news is that payroll becomes much easier when it follows a consistent process. This small business payroll checklist provides a practical framework for U.S. employers, covering what to prepare before payroll, what to review on payday, what to do after employees are paid, and which records need ongoing attention. Federal requirements are only part of the picture, so businesses should also check the rules that apply in their state and locality.
What Is a Small Business Payroll Checklist?
A payroll checklist is a repeatable list of tasks used to prepare, review, process, and close each payroll run.
Instead of treating payday as a single calculation, a reliable process separates payroll into several stages:
- Employee setup and records
- Time and pay review
- Payroll calculation
- Final approval
- Employee payment
- Tax deposits and filings
- Reconciliation and recordkeeping
This approach makes it easier to spot mistakes before they affect employees or tax records.
1. Complete Your Employer Payroll Setup
Before paying employees for the first time, make sure the business has completed the necessary employer setup.
For many employers, this includes obtaining an Employer Identification Number (EIN) and registering for applicable state or local tax accounts. The IRS also notes that states can have additional requirements beyond federal requirements.
Create a secure payroll file containing information such as:
- Legal business name
- EIN
- Business address
- Applicable state and local tax registrations
- Payroll bank account information
- Pay frequency
- Payroll processing dates
- Tax deposit and filing deadlines
Do this before the first payroll rather than trying to complete registrations while employees are waiting to be paid.
2. Collect the Right Information for Every Employee
Accurate payroll starts with accurate employee records.
For U.S. employees, employers generally need information related to employment eligibility, Social Security numbers, and federal income tax withholding. The IRS states that employers must properly complete Form I-9 for individuals they hire and should have Form W-4 on file for federal income-tax withholding.
Depending on the employee and business, your payroll records may include:
- Full legal name
- Social Security number
- Form W-4
- Form I-9 documentation
- Home address
- Pay rate or salary
- Pay frequency
- Benefits and deductions
- Direct-deposit information
- Relevant state tax information
Keep sensitive employee information protected and limit access to people who actually need it.
3. Confirm Employee Classification
Before processing wages, make sure workers have been classified correctly.
The distinction between an employee and an independent contractor can affect withholding, reporting, and employment-tax responsibilities. The IRS specifically advises businesses to determine the correct worker classification rather than treating classification as a simple choice made by the employer.
If a worker’s status is unclear, review the applicable IRS guidance or get professional advice before continuing.
A classification mistake can affect more than one payroll period, so it is better to address the issue during setup.
4. Build a Payroll Calendar
A payroll calendar turns payroll into a predictable routine.
For each pay period, set deadlines for:
- Employee time submission
- Manager approval
- Payroll adjustments
- Payroll review
- Payroll processing
- Employee payment
- Tax deposits
- Required filings
For example, if employees are paid every other Friday, the business might set an earlier deadline for timesheets so there is enough time to review overtime, absences, bonuses, and other changes.
Your calendar should include tax deadlines as well as paydays. Federal tax deposit schedules can vary based on the employer’s circumstances, so do not assume that the employee payday is also the tax deadline.
5. Review Everything That Changed During the Pay Period
This is one of the most important parts of the process.
Before calculating payroll, compare the current pay period with the previous one and look for changes.
Check:
- Regular hours
- Overtime
- Paid time off
- Unpaid leave
- New employees
- Departing employees
- Pay-rate changes
- Bonuses
- Commissions
- New deductions
- Benefit changes
- Wage garnishments or other required adjustments
A payroll system can calculate numbers quickly, but it cannot replace a review of the information entered into it.
6. Verify Hours and Overtime
For hourly employees, approved time records should be reviewed before payroll is finalized.
The U.S. Department of Labor says covered employers must maintain accurate records concerning hours worked and wages earned, including regular and overtime earnings.
Before moving forward, ask:
Are all hours included?
Was overtime recorded correctly?
Were approved time-off hours handled properly?
Does the payroll record agree with the employee’s time record?
These checks are particularly important when employees work different schedules or when managers submit time manually.
7. Calculate Gross Pay, Withholding, and Deductions
After the payroll inputs are approved, calculate each employee’s gross pay and applicable deductions.
Payroll may involve:
- Regular wages
- Overtime
- Bonuses
- Commissions
- Federal income-tax withholding
- Social Security and Medicare taxes
- State and local taxes where applicable
- Retirement contributions
- Health-plan deductions
- Wage garnishments
- Other authorized deductions
Federal employment taxes can include federal income tax, Social Security, Medicare, and federal unemployment tax. The IRS explains that employers have responsibilities for withholding, paying, depositing, and reporting applicable employment taxes.
The employee’s Form W-4 provides information used to determine federal income-tax withholding. If an employee submits a new W-4, employers should process it according to the applicable IRS rules.
8. Perform a Pre-Payroll Review
Before submitting payroll, stop and review the final payroll report.
This is the point where a simple checklist can prevent an expensive correction.
Look for:
- Unexpectedly high or low pay
- Missing employees
- Duplicate employees
- Unusual overtime
- Incorrect pay rates
- Missing deductions
- Unexpected bonuses
- Incorrect bank information
- Large differences from the previous payroll
A useful practice is to compare the current payroll totals with the previous period and investigate unusual changes rather than automatically approving them.
9. Make Sure Payroll Funding Is Available
Payroll should never be treated as an ordinary expense that can be funded at the last minute.
Before submitting employee payments, confirm that the business account has enough money for:
- Employee net pay
- Employer payroll costs
- Payroll tax obligations
- Other payroll-related payments
For businesses with uneven monthly revenue, planning for payroll dates in advance can help avoid cash-flow pressure.
10. Pay Employees on the Scheduled Date
Once payroll has been reviewed and approved, process employee payments according to the established schedule.
Depending on the business, payment may be made through direct deposit, checks, or another permitted method.
Keep the payroll register and payment records together so the business can later confirm:
- Who was paid
- How much was paid
- When payment was made
- Which pay period it covered
This creates a clear record if a payment needs to be investigated later.
11. Complete Payroll Tax Deposits and Filings
Employee payment is not the end of payroll.
Employers may need to deposit federal employment taxes and file required returns. The IRS explains that employers generally report wages and employment taxes using the appropriate forms, including Form 941 for many employers and other forms when applicable.
Your payroll process should therefore include:
- Checking the applicable deposit schedule
- Making required federal tax deposits
- Tracking state and local tax obligations
- Filing required payroll returns
- Saving payment confirmations
- Saving copies or evidence of submitted returns
Federal tax deposits generally must be made electronically, and the IRS provides several electronic payment options.
Because deadlines can vary, use the current IRS guidance and the applicable state or local agency rather than relying on a generic calendar.
12. Reconcile Payroll After Processing
After employees have been paid, compare the payroll records with the accounting and bank records.
Verify that:
- Net payroll matches actual payments
- Tax liabilities were recorded correctly
- Deductions were posted correctly
- Employer payroll expenses were recorded
- Payroll-related bank transactions match the payroll register
- Any unusual difference has been explained
This step is easy to skip when everything appears to have gone smoothly. It is also one of the best ways to discover a problem while the transaction is still easy to trace.
13. Keep Payroll Records Organized
Payroll records should be stored securely and consistently.
The IRS says employers generally need to retain employment-tax records for at least four years after filing the fourth quarter for the year. Required records can include wage amounts and dates, employee information, W-4 forms, tax-deposit records, filed returns, and other employment-tax documentation.
Federal wage-and-hour rules can have their own recordkeeping requirements, so employers should not assume that one retention period applies to every payroll document.
A well-organized system should make it easy to locate:
- Payroll registers
- Time records
- W-4 information
- Tax filings
- Tax payment confirmations
- Wage statements
- Deduction records
- Benefit records
- Employee changes
14. Review Payroll Quarterly
A quarterly review can identify problems that are difficult to notice one pay period at a time.
Compare:
- Payroll registers
- Tax deposits
- Payroll tax returns
- Accounting records
- Employee wage totals
- Benefits and deductions
For many employers, Form 941 is part of the quarterly federal payroll reporting process.
Use the review to investigate differences instead of carrying them forward into another quarter.
15. Prepare for Year-End Early
Year-end payroll should not begin after the final payroll of the year.
Before year-end reporting, review employee information, wage totals, tax withholding, benefits, and other compensation.
The IRS requires employers to prepare and furnish applicable wage statements such as Form W-2, with copies also reported to the Social Security Administration.
A useful year-end review includes:
- Employee names
- Social Security numbers
- Addresses
- Total wages
- Federal withholding
- Social Security and Medicare amounts
- Benefits and deductions
- Bonuses and other taxable compensation
- Payroll tax deposits
- Required information returns
Finding an error before year-end forms are prepared is usually easier than trying to correct inconsistent records afterward.
Small Business Payroll Checklist for Every Pay Period
Use this quick version when processing regular payroll:
| Payroll task | Check |
|---|---|
| Confirm pay period and deadline | ☐ |
| Collect and approve time records | ☐ |
| Check new hires and departures | ☐ |
| Verify pay-rate changes | ☐ |
| Review overtime and paid time off | ☐ |
| Check bonuses and commissions | ☐ |
| Review deductions and benefits | ☐ |
| Calculate gross and net pay | ☐ |
| Review unusual payroll changes | ☐ |
| Confirm payroll funding | ☐ |
| Approve and release employee payments | ☐ |
| Complete required tax deposits | ☐ |
| Record payroll in accounting | ☐ |
| Reconcile payroll and bank records | ☐ |
| Save payroll documentation | ☐ |
This list can be expanded or shortened depending on the size of the company, its payroll frequency, the states where employees work, and the types of compensation it provides.
Common Payroll Mistakes Small Businesses Should Avoid
Waiting until payday to check the numbers
Payroll should be reviewed before the final payment is submitted. Last-minute discoveries leave less time to correct mistakes.
Treating every worker the same
Employees and independent contractors can have different tax and reporting requirements. Classification should be addressed before payment.
Forgetting changes
Raises, new benefits, overtime, bonuses, and employee departures can all affect payroll.
Assuming software handles everything
Payroll software can automate calculations and repetitive tasks, but employers still need to provide accurate information and review the results.
Ignoring state and local requirements
A business can meet a federal requirement and still have additional obligations at the state or local level. The IRS specifically notes that states have their own requirements.
Keeping poor records
A business may need payroll records long after the original payday. Keeping documents organized and secure makes future reporting and problem-solving much easier.
When Should a Small Business Use Payroll Software?
Manual payroll may be manageable for a very small operation, but repetitive calculations, tax obligations, multiple employees, and changing schedules can quickly make the process harder to control.
Payroll software can help with tasks such as:
- Wage calculations
- Tax withholding
- Direct deposits
- Payroll reports
- Employee records
- Tax filing support
- Year-end forms
However, software should be viewed as a tool rather than a substitute for oversight. Employers remain responsible for providing accurate information and meeting the obligations that apply to their business.
Final Takeaway
A dependable payroll process is built around consistency.
The most effective approach is not simply calculating employee wages correctly. It is creating a system that starts with accurate employee records, checks hours and pay changes, reviews deductions, verifies the final payroll, completes required tax deposits and filings, and reconciles the results afterward.
Use this small business payroll checklist as a recurring workflow rather than a one-time setup document. Review it whenever the business hires employees, changes payroll systems, expands into another state, or introduces new forms of compensation. Click here for more information.
Payroll rules can change and requirements vary by jurisdiction, so U.S. employers should verify current federal, state, and local requirements before making decisions about their specific payroll situation.